



Term Plans
Protection-focused cover for a chosen period with death benefit


 Call to Buy 022 6537 6767
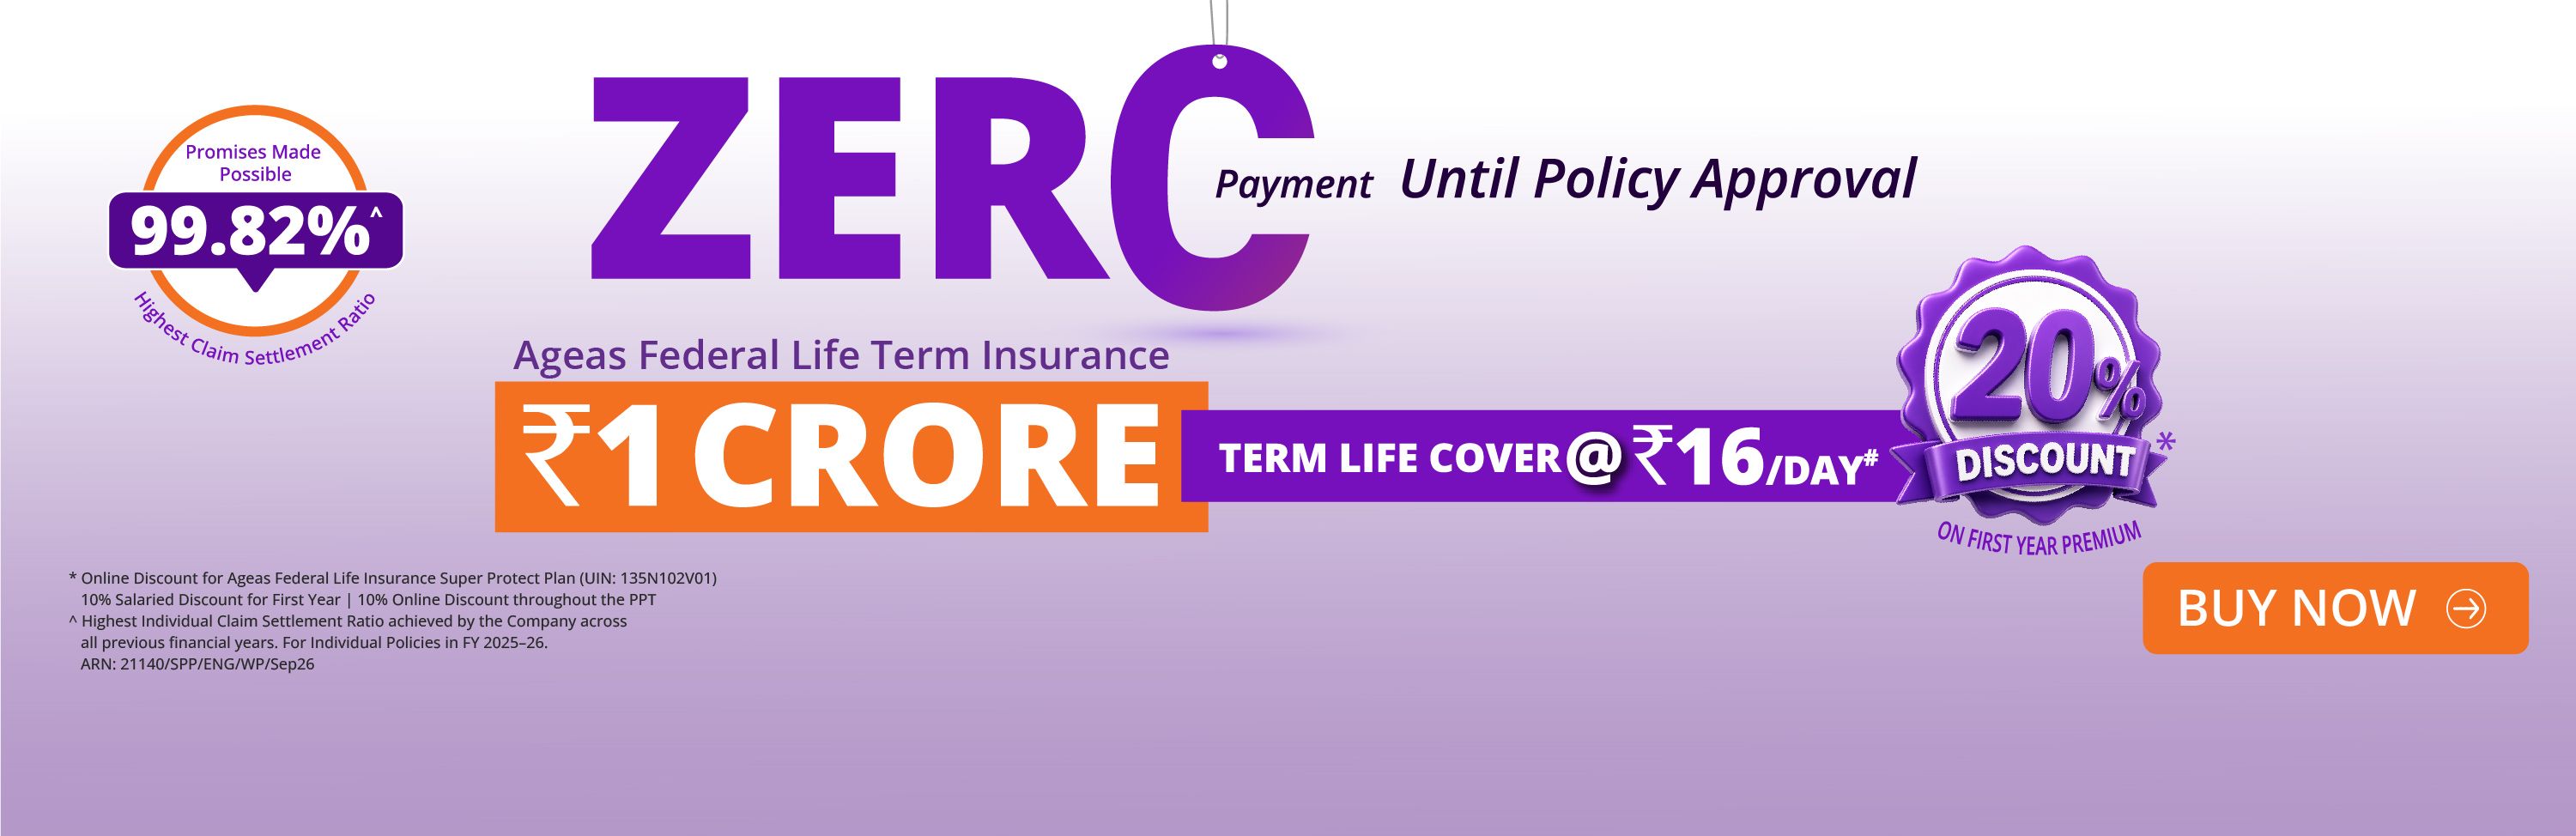
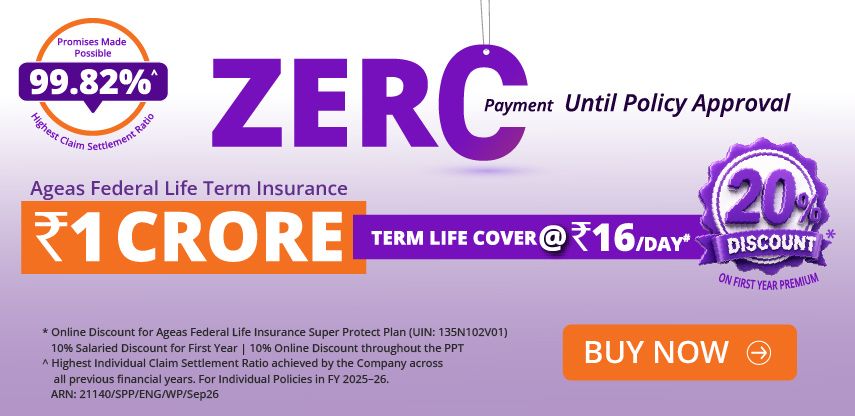
Protection-focused cover for a chosen period with death benefit
Life cover with market-linked investment funds & returns based on market performance
Life cover combined with structured long-term savings and policy benefits
Goal-led plans designed to support children’s milestones like higher education and marriage
Build a retirement corpus or provide regular income through pension or annuity
Protection solutions for eligible employees, borrowers or members under a master policy.
Affordable group cover with shared risk pooling & tailored benefits for every member
Quick & easy digital insurance with instant policy issuance & hassle-free management
99.82%
CLAIMS SETTLED
5M+
Customers
75+
Branches in India
5K+
Agents Nationwide
2025-2026
2025-2026
2025-2026
75% Settled Within 7 Days
Pick and choose the best life insurance plans online for your needs, or get hands on assistance from our advisors.
Honouring our motto “Har Wada Mumkin” with easy, hassle-free intimation, submission, and claim settlement process for your nominee.
The company states that it ranked among the top 10 in customer experience across the life insurance industry in the Hansa Research CuES 2026 report.
Hansa Research CuES 2026 report recognizes Ageas Federal for exceptional customer care.
Life insurance is a contract between a policyholder and an insurer. In return for the premiums paid, the insurer provides certain pre-decided benefits when a covered event occurs, subject to the policy terms.
The core purpose of life insurance is to deal with uncertainty of life. A classic life insurance policy ensures the nominee receives the death benefit if the life assured (i.e., the policyholder) passes away while an eligible policy is in force. However, there are other life insurance plans that also offer savings, market-linked growth, guaranteed benefits or retirement income depending on the product selected.
STEP 1
Select the purpose, plan type, cover amount and policy term.
STEP 2
Share accurate personal, financial, health and lifestyle information.
STEP 3
Keep the policy active by paying premiums as scheduled.
STEP 4
The applicable benefit is paid when the policy conditions are met.
BEST SELLERS
Your wish is our guarantee
Your dreams are our assurance
Save today for a secure future tomorrow
A death benefit can help dependents manage regular household expenses and maintain financial continuity after the loss of an earning member.
Adequate cover can help a family repay home loans, personal loans and other liabilities without being forced to sell assets earmarked for future goals.
The right policy can help protect plans for education, marriage, retirement or legacy creation when life does not unfold as expected.
STEP 1
Provide the policy number, life assured’s details, claimant details, date and cause of death.
STEP 2
Upload or provide the claim form, death certificate, claimant KYC, bank details and other requested records.
STEP 3
Share legible additional medical, hospital, accident or legal documents if the claims team asks for them.
STEP 4
Keep the acknowledgement and use the official tracking or support channel for updates.
STEP 1
Provide the policy number, life assured’s details, claimant details, date and cause of death.
STEP 2
Upload or provide the claim form, death certificate, claimant KYC, bank details and other requested records.
STEP 3
Share legible additional medical, hospital, accident or legal documents if the claims team asks for them.
STEP 4
Keep the acknowledgement and use the official tracking or support channel for updates.
Life cover can provide a financial cushion to nominees when the life assured dies during the policy term, subject to the contract.
Savings-oriented plans can encourage disciplined long-term contributions and offer policy benefits aligned with future milestones.
Depending on the product, policyholders may choose market-linked growth, guaranteed benefits, regular income or annuity options. Market-linked returns are not guaranteed.
Eligible premiums and policy proceeds may receive tax treatment under prevailing law, subject to product conditions, policy dates and the taxpayer’s circumstances.
Explore OUR plans
01
Pick protection, savings, growth, child planning or retirement.
02
Calculate your ideal cover, premium and affordability.
03
Complete the proposal with accurate personal information.
04
Upload documents and complete medical or underwriting checks.
05
Review your policy, make payment and save your documents.
Decide whether your first priority is family protection, savings, wealth creation, a child’s goal or retirement income.
Assess your family's monthly expenses, outstanding loans and future goals to arrive at a suitable sum assured and premium budget.
Compare term, endowment, ULIP and savings plans based on your protection needs, investment horizon and risk appetite.
Adults who meet a plan’s entry-age, income, health, residency, documentation and underwriting requirements may apply for life insurance. A policyholder may buy cover on their own life or, where permitted, propose a policy for another person with an insurable interest. Acceptance, premium and cover are decided after underwriting.
18-25 Yrs
Start personal protection early, cover education debt and begin long-term goal planning.
26-35 Yrs
Protect a spouse, parents or young family; cover a home loan; build savings for future milestones.
36-45 Yrs
Review a growing protection gap, children’s goals, business obligations and retirement savings.
46-55 Yrs
Reassess liabilities, dependents, legacy needs and the transition from accumulation to retirement planning.
56+ Yrs
Consider retirement income, estate needs and plan options available within product-specific entry-age rules.
*This is a life-stage guide, not an eligibility table. Entry-age, maturity age, medical requirements and available benefits vary by product.
Life protection is more affordable early in life, subject to health, underwriting and plan terms.
Adding enough cover to replace household income and protect shared plans makes sense.
Review whether the life cover amount could clear the liability without consuming other family assets.
Include education, childcare and the number of years the family may require support.
With higher income comes lifestyle upgrade. Hence, getting a life insurance policy helps cover the protection gap.
THE AGEAS FEDERAL MOBILE APP
Scan to
Download
Skip endless phone calls. File a life insurance claim digitally and track its status real time, from submission to payout.
Keep your life insurance plan active with zero friction and enjoy encrypted, online transactions in a few seconds.
From premium payment reminders to grace period. get smart, automated notification alerts customized to your schedule.
Connect with our support agents instantly to modify/update your policy details without visiting a branch office.
RESOURCES
Estimate the life insurance cover your family may need after considering income, liabilities and existing cover.
Estimate the premium for selected term cover and profile inputs.
Estimate the corpus that may be required to support retirement expenses.
Explore indicative retirement-income payouts based on selected inputs.
Project how regular or lump-sum investments may grow under assumed returns.
Compare common saving and compounding outcomes while planning broader financial goals.
Estimate the life insurance cover your family may need after considering income, liabilities and existing cover.
Estimate the premium for selected term cover and profile inputs.
Estimate the corpus that may be required to support retirement expenses.
Explore indicative retirement-income payouts based on selected inputs.
Project how regular or lump-sum investments may grow under assumed returns.
Compare common saving and compounding outcomes while planning broader financial goals.
INSIGHTS & RESOURCES
AGEAS FEDERAL LIFE INSURANCE
Endorsed by Life Insurance Experts
At Ageas Federal Life Insurance, we are dedicated to creating meaningful insurance solutions that help individuals build a secure and confident future. With over a decade of experience, we offer a wide range of plans across protection, pension, savings, investment, annuity, and health, designed to support evolving financial needs at every stage of life.
4.5
Reviews by 6000 customers
(Rate your experience on the website)
INSIGHTS & RESOURCES
No. Term insurance is one type of life insurance focused mainly on protection for a specified period. Life insurance also includes savings, ULIP, child, whole-life and retirement-oriented products.
There is no single best plan for everyone. The right option depends on your goal, cover gap, time horizon, risk tolerance, need for liquidity, budget and preference for guaranteed or market-linked benefits.
Estimate the income your family may need, outstanding debt and future goals, then subtract existing cover and assets earmarked for those needs. Use the HLV calculator as a starting point.
Yes. Eligible customers can compare plans, calculate premiums, complete forms, upload documents and pay through official online channels. Policy issuance remains subject to underwriting.
They may apply, but the insurer may request medical tests, charge a higher premium, apply conditions or decline the proposal. Full disclosure is required.
Yes, subject to financial underwriting and truthful disclosure of existing policies. The combined cover should remain supportable by income and insurable interest.
Policies normally provide a grace period specified in the contract. If payment is not made, the policy may lapse, become paid-up or continue with altered benefits depending on its terms.
Not automatically. Eligible premiums and receipts may receive tax treatment under the Income-tax Act, 2025, subject to policy and taxpayer conditions. Seek tax advice before relying on a benefit.
The claimant can intimate the insurer, provide policy and death details, submit mandatory documents and track the claim through official channels. Extra records may be required depending on the cause of death.
Review cover after marriage, parenthood, a major loan, income change, business obligation, change in residency or repayment of a large debt. A periodic review every few years is a useful habit.


Trending Searches


Copyright © 2026 Ageas Federal Life Insurance Co Ltd. All Rights Reserved.




